
Companies often respond to employee surveys by doubling down on what already scores well. New research suggests that this may be the wrong allocation strategy when the goal is stronger firm performance.
A study published in Strategy & Leadership on 29 September 2026 examined employee satisfaction across more than 900 publicly traded US companies over six years. The researchers found that firms with consistently strong satisfaction across multiple dimensions produced significant risk-adjusted abnormal stock returns, while firms with a more uneven pattern did not.
The distinction matters because both groups looked attractive in simpler market comparisons. Both portfolios outperformed the market, but only the balanced employee-satisfaction portfolio retained a statistically significant advantage after the researchers adjusted for investment risk.
The study looked beyond an average satisfaction score
Jonathan Matzinger and Harley Krohmer of the University of Bern, together with David Sprott of Claremont Graduate University, approached employee satisfaction as a configuration rather than a single average. Their analysis used multidimensional employee-satisfaction data from the Drucker Institute covering more than 900 publicly traded US firms across a six-year period.
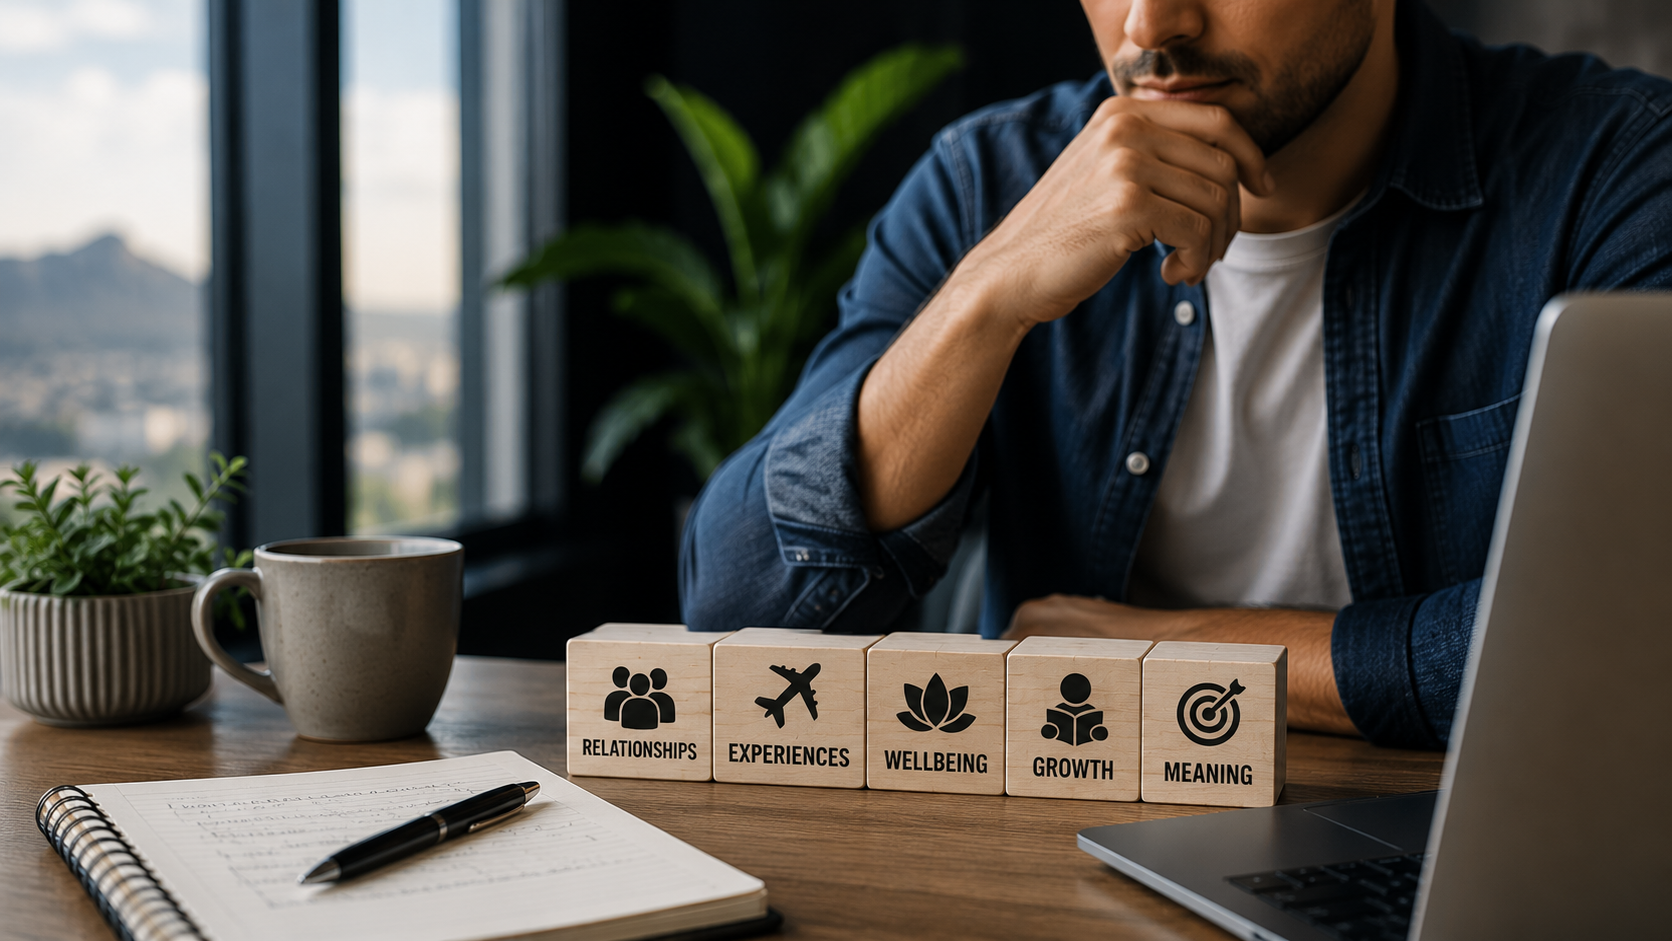
The researchers focused on the balance among five dimensions of employee satisfaction. This allowed them to distinguish firms that were consistently strong across dimensions from firms with exceptional ratings in some areas but weaker ratings in others.
That design tests two competing ideas about how satisfaction might contribute to performance. Under a compensatory logic, very strong performance in one dimension could make up for weakness elsewhere. Under a non-compensatory logic, a weak dimension could constrain the value created by stronger ones.
Stock portfolio analysis was then used to compare the subsequent market performance associated with these different satisfaction configurations. The key outcome was not simply whether a portfolio beat the market, but whether it generated abnormal returns after accounting for risk.
Balance mattered once investment risk was considered
Both the balanced and imbalanced portfolios outperformed the market in the researchers’ analysis. That initial result might appear to support the broad argument that high employee satisfaction is valuable regardless of how it is distributed across dimensions.
The risk-adjusted results were more selective. Only the portfolio representing a balanced employee-satisfaction gestalt generated statistically significant risk-adjusted abnormal returns. The imbalanced portfolio produced positive abnormal returns, but those returns were not statistically significant.
This means the evidence does not support a simple claim that every balanced company will outperform every uneven one. Portfolio-level statistical significance describes a pattern across the analysed firms and period, not a guaranteed return for an individual company or investor.
It does, however, challenge the idea that outstanding employee ratings in selected areas necessarily compensate for weaker parts of the employment experience. A company may score exceptionally well on some dimensions and still leave strategically important weaknesses unresolved.
Why the weakest dimension may deserve management attention
The practical implication is a resource-allocation problem. Employee initiatives compete for management attention and money, so leaders must decide whether the next rand or dollar should reinforce an existing strength or address an area where employees are less satisfied.
The study’s results favour the second approach when a clear imbalance exists. The authors argue that managers should prioritise comparatively weak satisfaction dimensions before allocating additional resources to areas that employees already evaluate favourably.
One reason is that employee experience can operate as a system. A strong development programme, for example, may not deliver its full organisational value if employees simultaneously experience serious weaknesses elsewhere in the employment relationship.
The research does not identify a universal weakest dimension that every firm should fix. Instead, its dispersion-based method asks whether a company’s five-dimensional profile is balanced or uneven. The strategic priority therefore depends on the firm’s own configuration.
The finding is relevant to firms measuring employee experience
Large organisations increasingly collect frequent employee-experience data, often producing dashboards with dozens of scores. Those systems can encourage managers to celebrate the highest-scoring measures or chase improvements in whichever metric receives the most executive attention.
This study suggests a different reading of the dashboard. The distance between dimensions may contain information that an overall satisfaction average conceals.
Two companies can achieve similar average satisfaction while having very different internal profiles. One may be consistently good across the measured dimensions, while another combines exceptional strengths with pronounced weaknesses. Treating those profiles as equivalent can hide the possibility that the weakest element constrains the whole system.
For South African employers, the study is not a direct estimate of local firm performance because the sample consists of publicly traded US companies. Its more transferable contribution is analytical: employee satisfaction can be examined as a pattern of complementary dimensions rather than reduced to a single headline score.
There are important limits to the conclusion
The research is observational and links satisfaction configurations with subsequent stock-market outcomes. It cannot prove that balancing employee satisfaction caused the abnormal returns. Other organisational characteristics may contribute to both stronger employee experiences and stronger market performance.
The authors also highlight a limitation in how balance was measured. Their dispersion-based operationalisation captures whether satisfaction dimensions are relatively balanced or imbalanced, but it does not reveal which specific dimensional combinations are responsible for the observed performance pattern.
Future research can therefore move from broad balance to profile-specific analysis. That could establish whether particular combinations of strengths and weaknesses are especially consequential, and whether the pattern holds in private companies, smaller firms and markets outside the United States.
The six-year, 900-plus-firm dataset nevertheless provides a substantial test of the central idea. The strongest signal did not come from firms that were simply excellent somewhere. It came from the portfolio of firms whose employee satisfaction was consistently strong across the dimensions being measured.
For managers, that reframes employee satisfaction from a competition to produce the highest possible score on a favoured metric into a question of organisational coherence. Before investing more in an existing strength, the more valuable question may be whether another part of the employee experience is holding the overall system back.
Source Information
Study Title: Address weaknesses or reinforce strengths? The gestalt of employee satisfaction and its impact on firm performance
Authors: Jonathan Matzinger, Harley Krohmer and David Sprott
Journal: Strategy & Leadership
Year: 2026
Published: 29 September 2026
DOI: 10.1108/SL-07-2026-0380
Study design: Multidimensional employee-satisfaction analysis and stock portfolio analysis covering more than 900 publicly traded US firms over six years.