Financial abuse can leave consequences that extend far beyond a single bank account.
It can erode savings, increase debt, damage credit and restrict a person’s ability to make independent financial decisions.
New research suggests that some of these changes can be visible in banking records years before victim-survivors formally disclose the abuse to their bank.
A study published in Nature on 23 September 2026 analysed anonymised records from a major UK retail bank. The researchers compared 5,428 women who had disclosed financial abuse with 15,602 matched women who had no known disclosure.
The analysis covered seven years before disclosure and examined 373 transactional and non-transactional indicators.
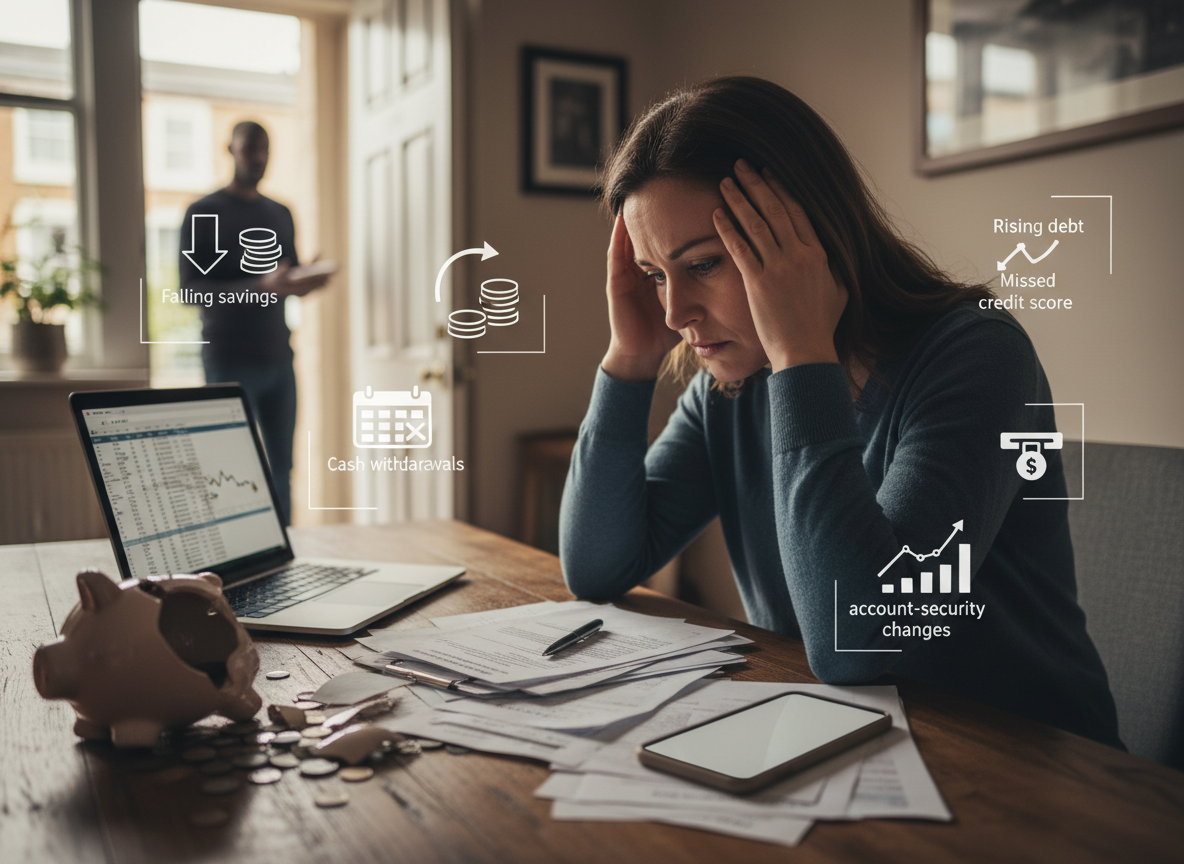
Compared with matched controls, victim-survivors showed progressively depleted savings, greater borrowing, more missed payments and worsening credit scores. They were also more likely to withdraw cash, change passwords and addresses, incur legal and transport costs, interact more frequently with the bank and receive welfare benefits.
The study provides unusually detailed evidence of how financial abuse can coincide with a gradual loss of financial independence.
But the patterns should not be treated as a diagnostic test for abuse. Similar financial behaviours can occur for many reasons, and the study identified victim-survivors through disclosures rather than independently establishing when abuse began.
Financial abuse is more than simply having less money
Financial abuse is a form of domestic abuse involving control over money and financial resources.
It can involve restricting access to bank accounts, rationing money, creating debt in another person’s name, interfering with employment, controlling welfare payments or damaging a victim-survivor’s credit history.
These behaviours can make it harder for someone to leave an abusive relationship because financial independence is often necessary for housing, transport, legal support and everyday living expenses.
Previous research has documented these experiences mainly through interviews and surveys.
Those methods are essential for understanding coercion and lived experience, but they cannot always reconstruct detailed financial behaviour across many years.
The new study approached the issue from a different direction by examining administrative banking data.
The researchers followed financial behaviour across seven years
The victim-survivor group consisted of 5,428 female customers who disclosed financial abuse to a major UK retail bank.
The researchers matched them with 15,602 customers who had no known disclosure and who had similar demographic and socioeconomic characteristics seven years before the disclosure point.
This matching strategy was designed to make the groups more comparable before the later financial patterns emerged.
The researchers then examined how the two groups differed as the disclosure date approached.
Rather than focusing on only account balances or debt, the study incorporated 353 transaction categories and 20 non-transactional banking indicators.
Together, these produced 373 outcomes spanning income, savings, borrowing, spending, account security, interactions with the bank and other financial behaviours.
Savings fell while debt pressures increased
One of the clearest patterns was declining financial resilience.
Victim-survivors had lower savings balances than matched controls and increasingly relied on borrowing as disclosure approached.
They showed higher planned overdrafts, more credit-card interest activity, more loan repayments and more overdraft charges.
They were also more likely to apply for credit cards and loans during the pre-disclosure period.
The researchers found no evidence that those applications were more likely to succeed, suggesting that increased debt exposure may partly reflect greater demand for credit rather than easier access to it.
Over time, the financial strain culminated in more missed payments and lower credit scores.
Missed payments became much more common
The scale of the financial instability becomes especially visible when the victim-survivor group is compared with the bank’s wider customer population.
In the year before disclosure, 63% of victim-survivors had at least one missed direct debit, compared with 17% in the wider bank population.
The researchers describe this as a 279% higher prevalence.
Credit scores were also lower.
The average credit score among victim-survivors was 767 compared with 960 in the wider bank population used for context.
These figures do not show that financial abuse alone caused every missed payment or credit-score decline.
They do show that substantial financial distress was concentrated among the women who later disclosed abuse.
Savings were dramatically lower by the year before disclosure
The same pattern appeared in savings.
Victim-survivors had average savings of £3,088 in the year before disclosure, compared with £14,215 in the broader bank population.
That represents a 78% lower average savings balance.
When compared specifically with the matched control group, the researchers also found a significant savings gap.
Lower savings matter because they reduce the financial buffer available when someone needs to relocate, replace essential items, pay legal costs or manage a sudden loss of household income.
In the context of domestic abuse, the erosion of savings can therefore have practical consequences for a victim-survivor’s ability to leave or rebuild independently.
Welfare reliance increased sharply
The study also identified large differences in welfare-benefit receipt.
In the year before disclosure, 51% of victim-survivors received Universal Credit compared with approximately 10% in the wider bank population.
The researchers reported a difference of 28.4 percentage points between victim-survivors and the matched control group.
Disability-benefit receipt was also higher.
This may reflect multiple pathways, including disrupted employment, health vulnerabilities and the broader economic consequences of abuse.
The study cannot identify one single mechanism behind these welfare patterns.
But they reinforce the finding that financial abuse often occurs alongside wider economic instability.
Account-security behaviour changed as well
The findings were not limited to spending and balances.
Victim-survivors changed passwords and addresses more frequently than matched controls.
They were also more likely to reorder PINs and report lost or stolen cards.
These behaviours are consistent with circumstances in which control over an account is contested, compromised or being re-established.
However, the meaning of any individual event cannot be inferred from the transaction record alone.
People change passwords, replace cards or move address for many ordinary reasons.
The importance lies in the broader pattern across a group of customers who later disclosed financial abuse.
Victim-survivors interacted with their bank more often
The victim-survivor group also showed increased contact with the bank through branches, telephone channels and internet banking.
Fraud-related and complaint-related remedial payments were more common as well.
These interactions could be especially important for banks because they represent moments when financial distress or account-control problems become visible.
Previous research cited by the authors suggests that some victim-survivors are more likely to disclose financial abuse to a bank than to the police or a domestic-abuse service.
That places financial institutions in an unusual position.
They are not domestic-abuse investigators, but they may be among the first organisations to encounter the financial consequences.
Spending patterns also shifted
The study found differences in how money was spent.
Victim-survivors spent less in some self-care categories and more on legal and transport-related costs.
They also made more cash withdrawals.
These changes could reflect constrained access to shared finances, increased mobility needs, separation-related costs or efforts to manage money outside ordinary household patterns.
The banking data alone cannot determine the reason behind each transaction.
The study therefore interprets these behaviours in combination with existing qualitative research on financial abuse rather than treating each transaction category as direct evidence of coercion.
The researchers tested whether ordinary financial distress could explain the pattern
A major challenge is distinguishing the consequences of financial abuse from severe financial hardship more generally.
Someone experiencing unemployment, illness or a relationship breakdown may also show rising debt, missed payments and lower savings.
The researchers therefore conducted additional analyses using a control sample matched more closely on financial distress.
Several differences remained, including higher benefit receipt, cash withdrawals, account-access and security activity and more frequent interactions with the bank.
The authors also used a relationship-end-matched comparison to test whether separation itself could account for some of the results.
These sensitivity analyses strengthen the argument that the observed patterns are not explained entirely by generic financial distress or relationship breakdown.
The study still cannot identify exactly when abuse began
The disclosure date is a practical anchor for the analysis, but it is not necessarily the date when financial abuse started.
Some victim-survivors may have experienced coercive financial behaviour for months or years before telling the bank.
Others may have disclosed relatively soon after the abuse escalated.
The banking records therefore show how financial circumstances changed in the years before disclosure, not a precise timeline beginning at the onset of abuse.
This distinction is essential when interpreting the gradual divergence between victim-survivors and controls.
The control group may include people who never disclosed abuse
Another important limitation comes from how the groups were defined.
Victim-survivors were identified because they disclosed financial abuse to the bank.
The control group consisted of customers with no known disclosure.
No known disclosure does not guarantee that abuse was absent.
Some people experiencing financial abuse may never tell their bank, police, friends or support services.
If undisclosed victim-survivors were present in the control group, the differences between the groups could actually be harder to detect.
It also means the findings are most directly applicable to people whose circumstances eventually led to a bank disclosure.
The sample included women, so the results should not be generalised to everyone
The primary victim-survivor sample was female.
Women are disproportionately affected by domestic abuse, but men and people of other genders can also experience financial abuse.
The study therefore cannot establish that the same banking patterns occur with the same frequency or intensity across all victim-survivor groups.
The data also came from one major UK retail bank.
Banking systems, welfare programmes, credit markets and domestic-abuse support structures differ between countries.
The exact figures should not be assumed to apply directly to South Africa or other financial systems.
These patterns should not become an automatic abuse score
The study raises an obvious technological possibility: could banks use transaction data to identify customers who may need help?
That possibility requires considerable caution.
Debt, cash withdrawals, password resets, welfare payments and missed direct debits are not unique to financial abuse.
An automated system that treats these behaviours as proof of abuse could wrongly label customers, create privacy concerns or even increase danger if interventions are poorly designed.
The research is better understood as evidence that banks may have multiple opportunities to offer carefully designed support when customers show signs of vulnerability or disclose abuse.
Any data-driven intervention would need strong safeguards, human oversight and input from victim-survivors and domestic-abuse specialists.
Banks may be able to reduce some of the financial damage after disclosure
The findings have practical implications even without predictive monitoring.
Once financial abuse is disclosed, banks can review account access, debt, card security, password controls, joint accounts and communication preferences.
They can also examine whether ordinary collections processes or fraud procedures unintentionally create additional barriers for someone trying to regain financial control.
The study shows that by the time disclosure occurs, some victim-survivors may already have experienced years of deteriorating financial stability.
Support therefore needs to address not only immediate account security but also the longer-term consequences of damaged savings, debt and credit history.
The bigger lesson is that financial abuse can accumulate quietly
Financial abuse does not always appear as one dramatic transaction.
It can emerge as a gradual loss of flexibility and independence.
Savings decline. Borrowing rises. Payments are missed. Credit deteriorates. Account-control activity increases. Welfare support becomes more important.
No single one of these changes proves abuse.
Together, however, the new study shows that the financial lives of women who later disclosed abuse diverged substantially from those of otherwise similar customers.
That gives researchers and financial institutions a more concrete picture of what financial coercion can look like over time—and of how long the economic consequences may be building before anyone outside the relationship is told.
Source Information
Study Title: Banking records reveal characteristics of financial abuse
Authors: Anna Trendl, Nicola Sharp-Jeffs, Karen Perrier, Jane Rodrick, John Gathergood and colleagues
Journal: Nature
Published: 23 September 2026
Sample: 5,428 female customers who disclosed financial abuse to a major UK retail bank and 15,602 matched controls with no known disclosure. Additional distress-matched and relationship-end-matched samples were used in sensitivity analyses.
Method: Retrospective longitudinal analysis of anonymised individual-level banking records over the seven years before disclosure. Researchers analysed 373 transactional and non-transactional outcomes spanning income, savings, debt, spending, account security and interactions with the bank, using matched comparison groups to examine how financial patterns diverged over time.
Main finding: Compared with matched controls, victim-survivors showed declining savings, increasing borrowing and financial strain, more missed payments and worsening credit scores before disclosure. They also showed higher welfare reliance, more cash withdrawals, more account-security changes and more frequent interactions with the bank. The patterns were associated with later disclosure of financial abuse but are not individually diagnostic of abuse.
DOI: 10.1038/s41586-026-11049-7